


Josh Le, , CFA, MSc in FE
The MSCI AC World Equities (ACWI) declined modestly in July (-0.3%), rebounded in August (+2.7%), and retreated again in September (-1.2%), ending the quarter with a cumulative gain of approximately +1.2% (YTD: +12.9%). Nonetheless, the macro backdrop remained challenging, heavily influenced by elevated interest rates (with the 10-year treasury yield exceeding 5.3%), the Fed’s first rate hike since 2023, and the ongoing US-Iran conflict, which continued to put upward pressure on energy prices and inflation.
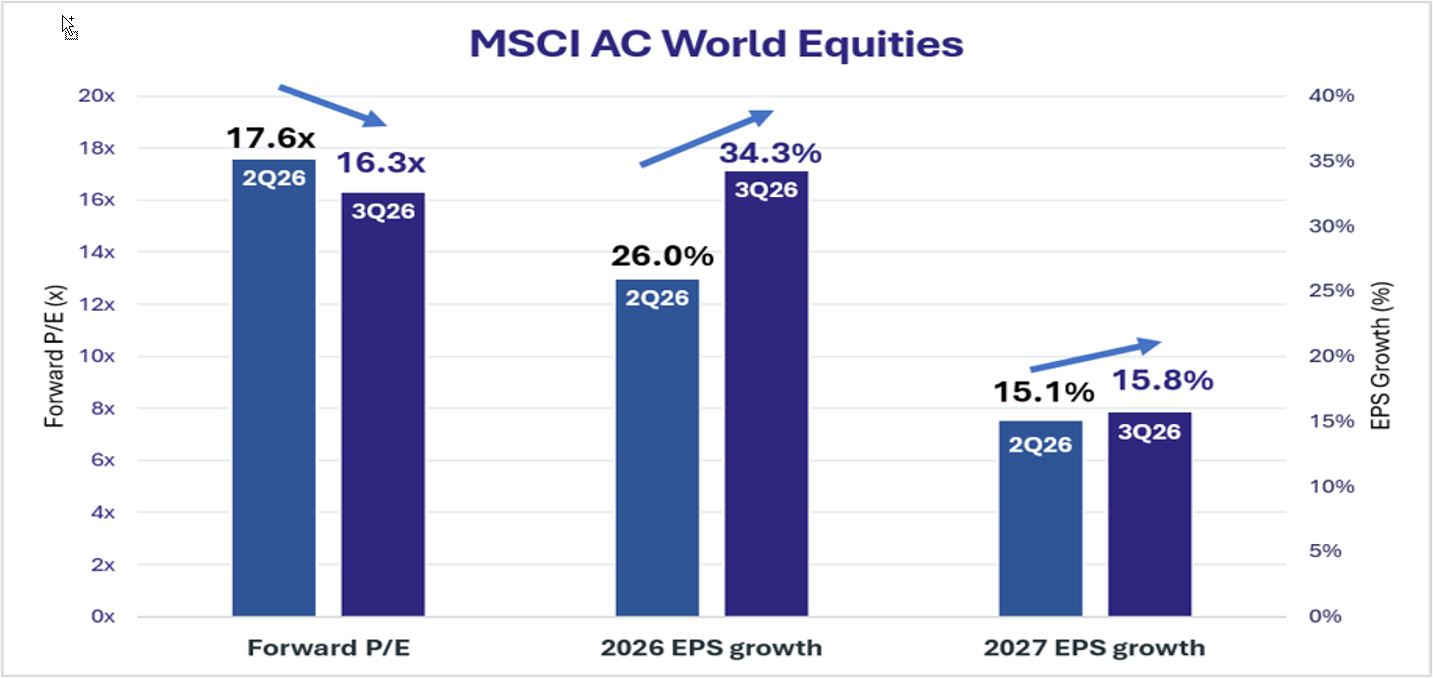
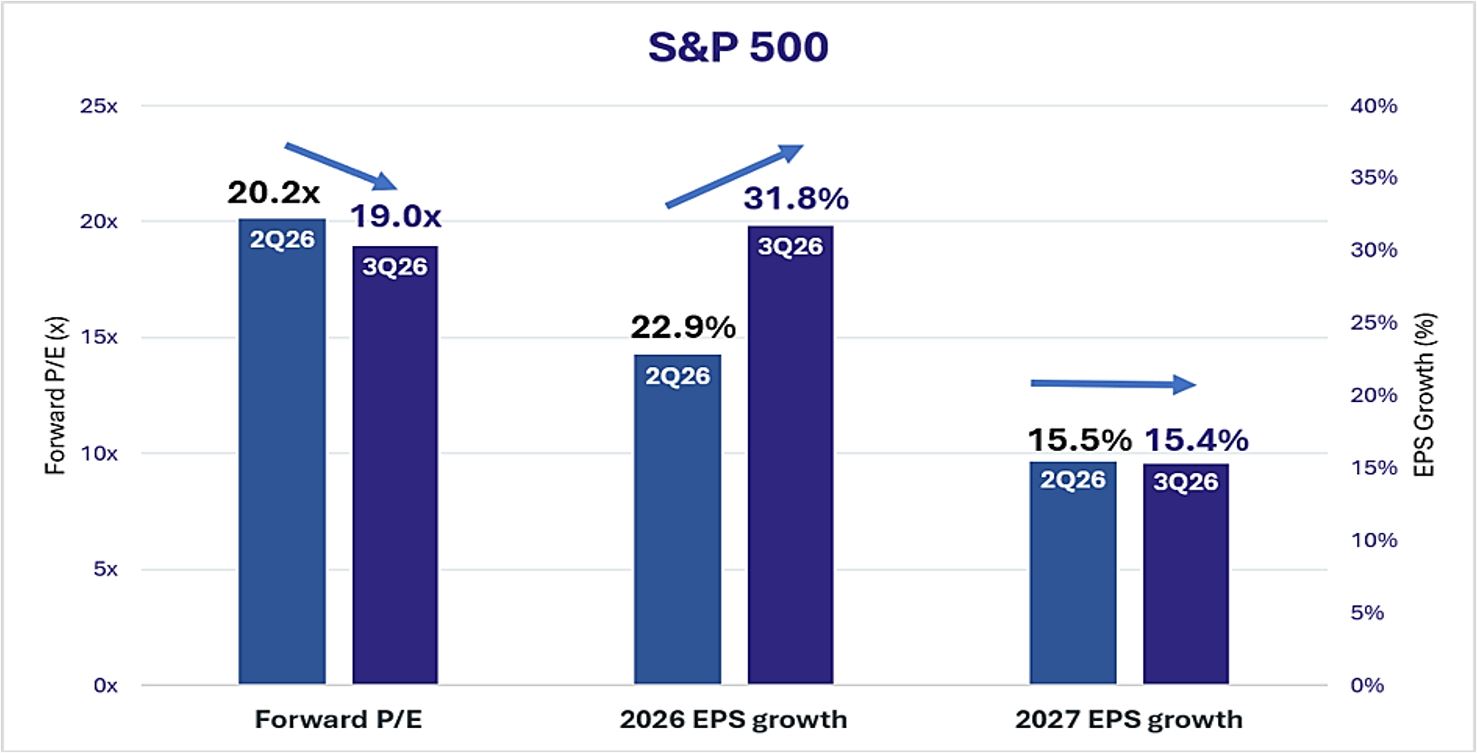
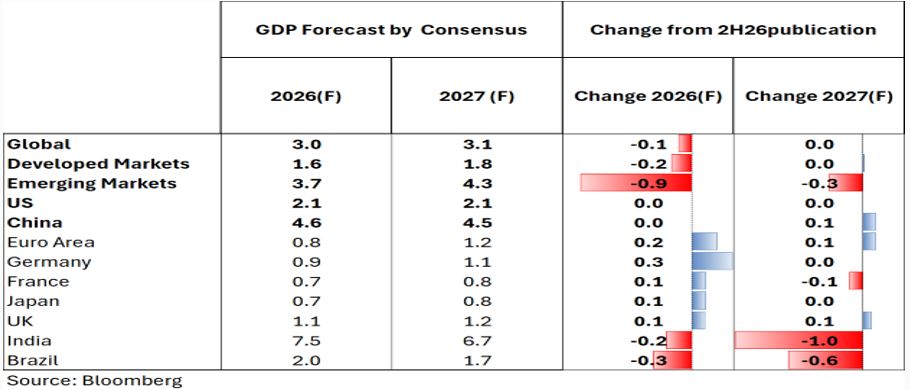
In contrast, corporate earnings have remained remarkably resilient, with positive equity returns continuing to be underpinned by strong earnings momentum. During 3Q26, expectations for CY26 EPS growth for the S&P 500/MSCI AC World indices were revised upward to +32%/+34% yoy, respectively, from +23%/+26% in 2Q26. Despite these substantial earnings upgrades, valuations have become even more attractive, with forward P/E multiples declining to 19.0x/16.3x, respectively, from their 2Q26 levels (figure 1 & 2). This combination of accelerating earnings growth and valuation compression has further strengthened the market’s fundamental risk-reward profile.
In term of price action, the Nasdaq and the semiconductor sector (SOX) both experienced sharp drawdowns in July, with the SOX index falling by roughly -26% peak-to-trough, while the Nasdaq declined -6.6%. Beyond macro concerns, several events contributed to the selloff, beginning with the unwinding of leveraged ETFs linked to memory stocks and disappointing post-IPO performance from SpaceX. These events subsequently snowballed into the liquidation of Situational Awareness fund and broader de-grossiang across the tech exposure.
Nevertheless, as discussed in the next section, we stick to our view that AI adoption and CapEx will continue to be strong going forwards. This should underpin revenue and free cash flow growth for our AI pick-and-shovel companies, some of which are also well positioned to increase shareholder returns. Against this backdrop, we view the recent correction in semiconductor stocks as an attractive opportunity to selectively add to our high conviction positions.
AI adoption showed no signs of slowdown, with Anthropic’s annualized revenue run-rate (ARR) reaching $67bn this quarter. In addition, Nvidia also reported that nearly 20 companies had surpassed $1bn in ARR, up from 13 in 4Q25, underscoring the broadening AI ecosystem. Some of these points have been highlighted in our previous quarter’s commentary.
Among the mega-cap hyperscalers, Microsoft, Alphabet, and Amazon have demonstrated their ability to re-accelerate the cloud business’ growth and backlog: Google Cloud +82% yoy, Microsoft Azure +43% yoy, and Amazon AWS +37% yoy. Remarkably, Microsoft has managed to bring online 3 GW new data center capacity in the last 3 quarters.
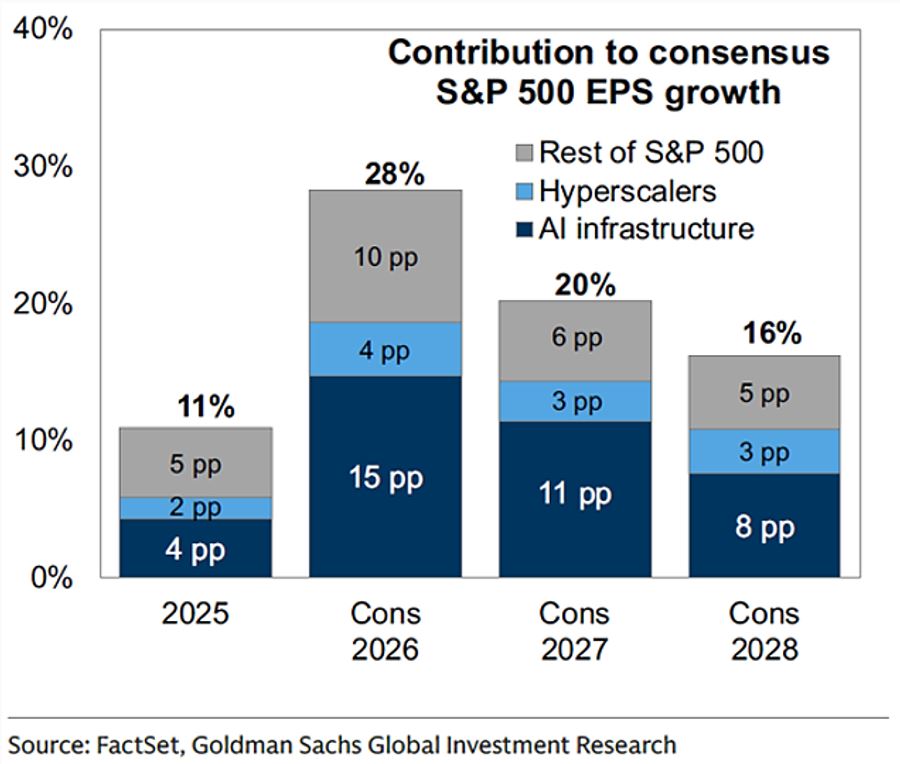
At the current expectations, more than half of the S&P 500’s EPS growth exclusive of “other incomes” in CY26 and CY27 is to come from “AI infrastructure” companies. As a result, it necessitates a close watch on the most crucial driver of the “AI infrastructure” layer: the AI CapEx cycle.
In our base case, we believe that AI CapEx will remain on a strong growth trajectory in CY27, further supported by 3 potential upside drivers: higher-than-consensus CapEx by hyperscalers, continuous expansion of global neoclouds, and a longer-term ramp in regional neoclouds/sovereign AI deployments.
First, the hyperscalers (Amazon, Microsoft, Alphabet, Meta, and Oracle) are currently expected to increase CapEx to ~$1.1tn in CY27 (+37% yoy), a strong starting point in itself (figure 4).
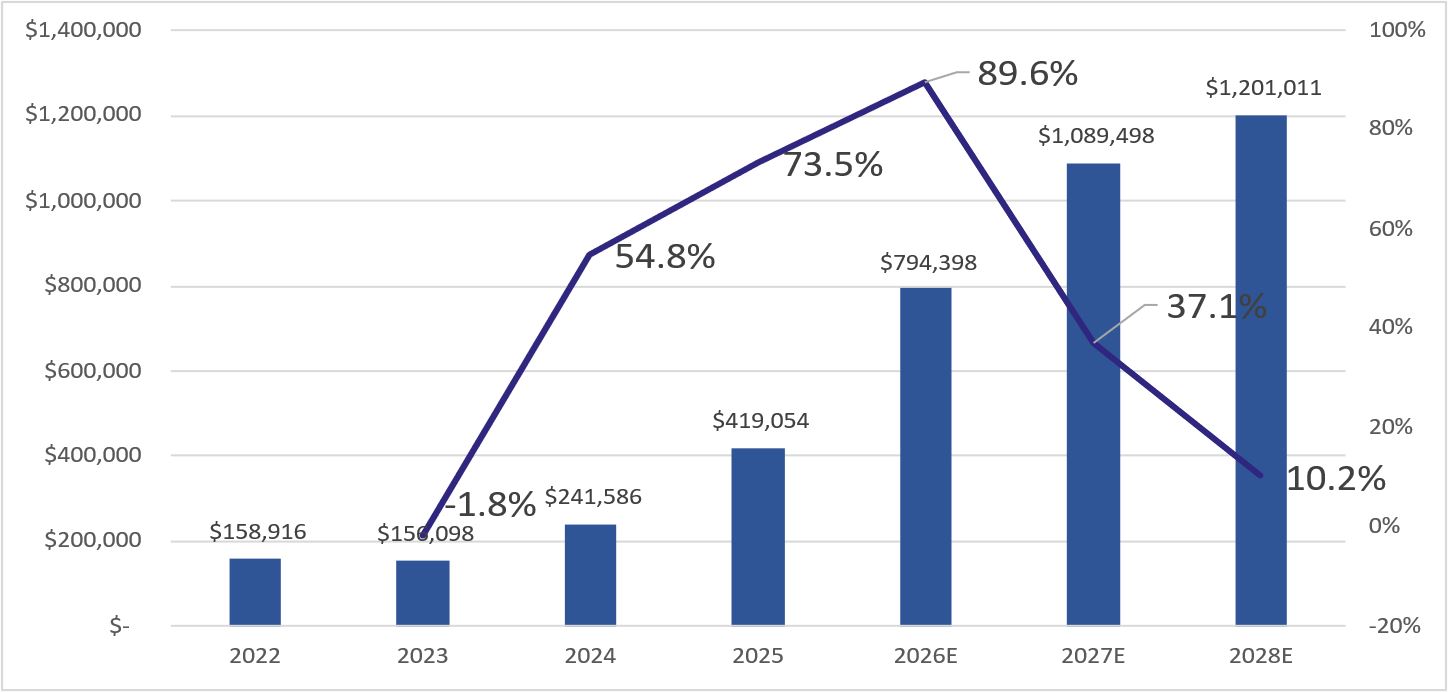
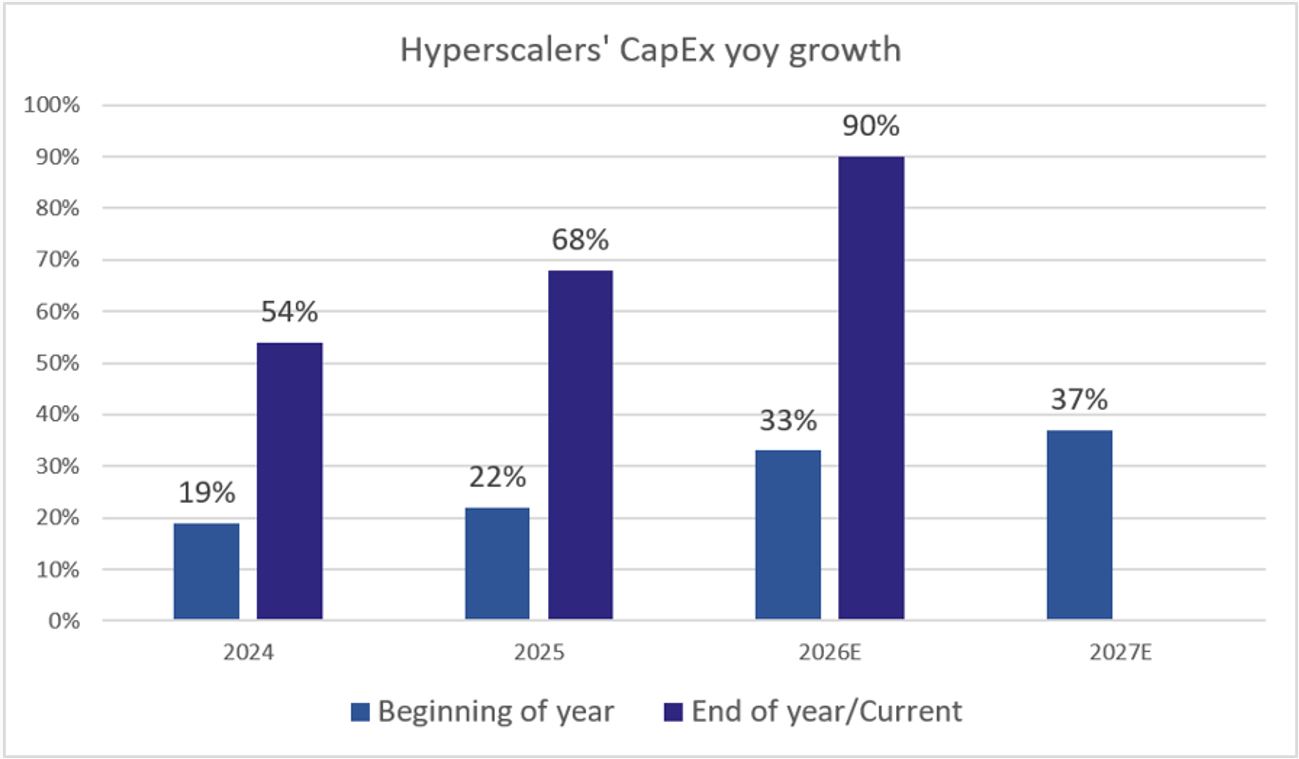
Moreover, hyperscaler CapEx has exceeded consensus estimates significantly for 3 consecutive years with yoy growth rate tracking +54%/+73%/+96% in 2024A/2025A/2026E, respectively, compared with beginning-of-year forecasts of +19%/+22%/+36% (figure 5). Given this track record, it would not be surprising to see CapEx growth once again exceed the currently forecast of +37% yoy in 2027.
In addition, reverse-engineered estimates based on hyperscaler CapEx imply datacentre capacity net additions of ~22GW in 2027 and ~24GW in 2028 (We assume $50bn/GW total build costs for 2027 & 2028). Put differently, current market expectations already incorporate roughly a 30% delay relative to planned capacity additions due to power and chip shortages. These conservative assumptions continue to leave room for further upside surprises from hyperscaler investment.
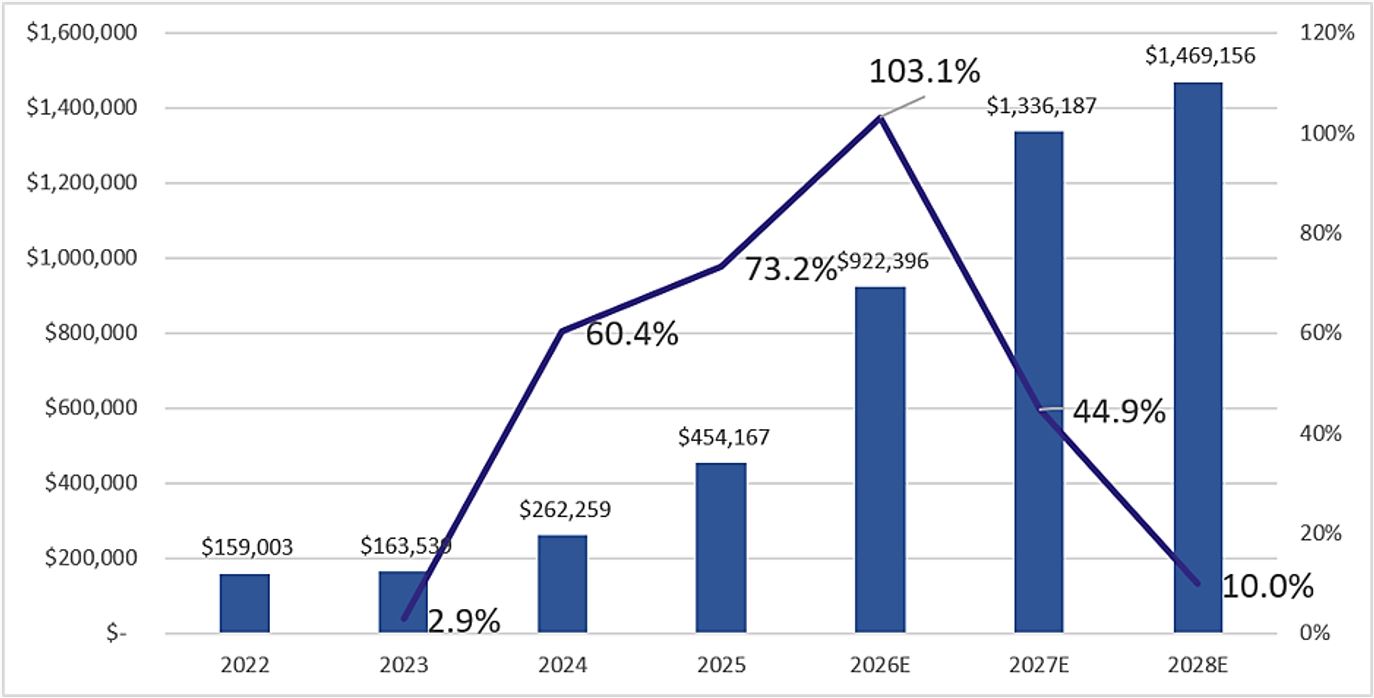
Second, listed neoclouds (Coreweave, Nebius, and SpaceX) will expand datacenter capacity and CapEx in 2027 as well. Their management teams have consistently highlighted attractive economics, including short payback periods (2-3 years) and compelling ROIC on their new deployments. Incorporating both these global neoclouds and hyperscalers, we forecast AI CapEx growth of ~+45% yoy 2027 (figure 6).
Finally, sovereign AI initiatives continue to gain momentum across multiple regions, with governments committing substantial resources to develop domestic AI capabilities: South Korea’s $900bn national AI plan, Japan’s $2.3tn growth strategy, the EU’s AI factories, UAE’s G42/Stargate project, and Saudi Arabia’s project HUMAIN. These nations’ AI programs, together with the emergence of regional neocloud champions such as Australia’s Firmus, Taiwan’s GMI Cloud, India’s Yotta and Neysa … are laying the foundation for a new wave of AI infrastructure investment in the future.
Taken together, we believe that AI infrastructure spending is unlikely to peak in the near term. This should support another year of robust earnings growth across our AI shovel-makers and the overall market in 2027. Nonetheless, from an investment perspective, we favour selective hyperscaler names over neoclouds, given the latter’s greater reliance on leverage and weaker operating cash flow generation.
In 3Q26, as hyperscalers and semiconductor stocks came under pressure, the baton was passed to software companies. The software sector rallied +17.5% during this period, sharply outperforming the Semiconductor Index (SOX), which declined -11.2% (figure 7). As a result, the majority of the GEP’s gains this quarter came from the software sector.
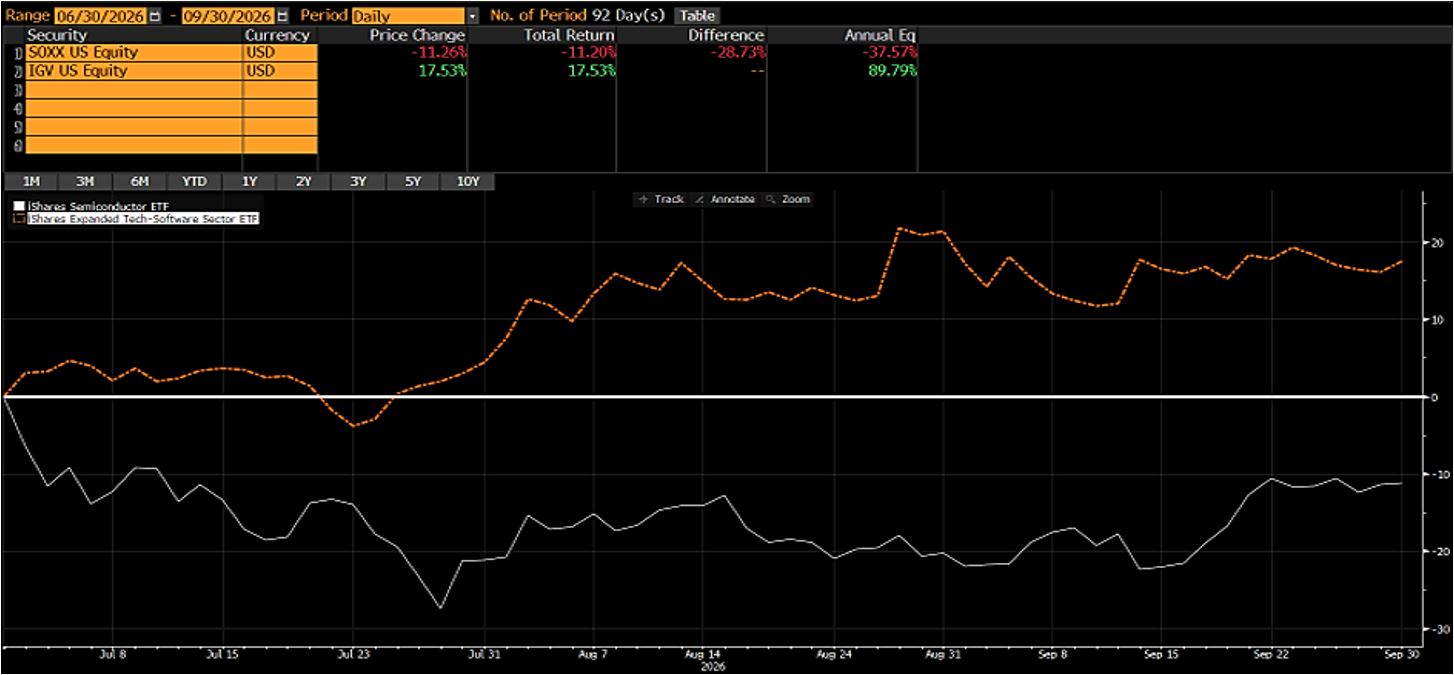
Solid earnings from software companies have debunked “SaaS-pocalypse” concerns, driving the recent re-rating. MongoDB reported robust +30% yoy growth in its Atlas revenue, while Snowflake accelerated revenue growth from 34% to 37% yoy, supported by rising AI-related demand.
Snowflake dispelled concerns that AI would cannibalize data platform spend. Instead, AI acted as a structural multiplier. As enterprises deployed internal coding and data agents (such as CoCo and CoWork) to automate complex data tasks, underlying data query and storage consumption accelerated sharply.
Cloudflare highlighted a major milestone in digital infrastructure: over half of all global traffic flowing across its network is now non-human machine traffic generated by AI agents. This shift positions lightweight, edge runtime platforms as the essential execution environment for the agentic web.
Datadog showed that AI adoption is re-accelerating core non-AI cloud modernization alongside AI natives. As autonomous agents interact with databases and external APIs through tools like the Model Context Protocol (MCP), tracking model health, tool calls, and infrastructure bottlenecks has become mission critical.
Several of our lagging positions, including Microsoft and ServiceNow, also rebounded strongly during the month. In our view, both remain high-quality businesses whose share prices had been weighed down by overly pessimistic sentiment surrounding the “SaaS-pocalypse”.
The narrative has now shifted from proving relevance to executing the transition from seat-based revenue models toward consumption-based monetization. We therefore remain focused on businesses with durable moats, particularly mission-critical, infrastructure, and enterprise software providers. By contrast, companies that function primarily as “AI wrappers” or “systems of engagement” face a greater risk of commoditization.
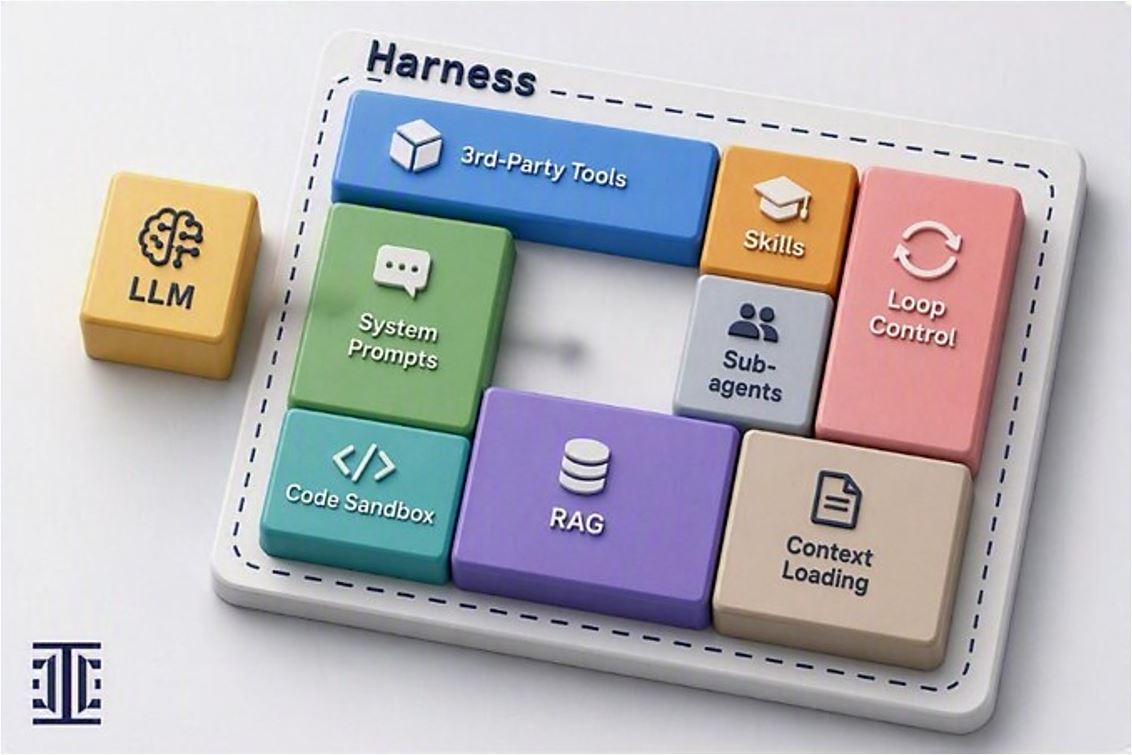
Lastly, the AI “harness” has become increasingly key as agentic AI trend progresses. An AI harness of the infrastructure built around the large language model (LLM) to turn reasoning into reliable action, including APIs and tool calls, memory management, code sandbox, guardrails, and loop control. In an agentic AI system, the LLM acts as the brain, while the harness functions as the limbs. Hyperscalers, in partnership with software companies, are central to building and monetizing this AI harness.
In summary, despite heightened macro uncertainty, we remain constructive on the equity market, underpinned by strong fundamental momentum, including resilient corporate earnings, accelerating AI adoption and improving return on investment (ROI). As highlighted in our 2Q review distinguishing between price momentum – often driven by shifting investor sentiment and market greed & fear – and fundamental momentum is critical to generating sustainable long-term returns. More importantly, we believe the AI investment cycle remains firmly intact through 2027, with sustained infrastructure spending supporting robust growth opportunities for our hardware and software infrastructure enablers. Against this backdrop, we view market volatility not merely as a risk, but also as an opportunity to selectively add to our highest-conviction positions at attractive valuations.
Josh Le, CFA, MSc in FE
Senior Vice President
Portfolio Manager
joshle@covenant-capital.com
Risk Disclosure
Investors should consider this report as only a single factor in making their investment decision. Covenant Capital (“CC”) may not have taken any steps to ensure that the securities or financial instruments referred to in this report are suitable for any particular investor. CC will not treat recipients as its customers by their receiving the report. The investments or services contained or referred to in this report may not be suitable for you and it is recommended that you consult an independent investment advisor if you are in doubt about such investments or investment services. Nothing in this report constitutes investment, legal, accounting, or tax advice or a representation that any investment or strategy is suitable or appropriate to your circumstances or otherwise constitutes a personal recommendation to you. The price, value of, and income from any of the securities or financial instruments mentioned in this report can fall as well as rise. The value of securities and financial instruments is affected by changes in a spot or forward interest and exchange rates, economic indicators, the financial standing of any issuer or reference issuer, etc., that may have a positive or adverse effect on the income from or the price of such securities or financial instruments. By purchasing securities or financial instruments, you may incur above the principal as a result of fluctuations in market prices or other financial indices, etc. Investors in securities such as ADRs, the values of which are influenced by currency volatility, effectively assume this risk.
By entering this site you agree to be bound by the Terms and Conditions of Use. COVENANT CAPITAL PTE LTD (“CCPL”) is a Capital Markets License (AI/II) holder and regulated by the Monetary Authority of Singapore (‘MAS’).
By using this site you represent and warrant that you are an accredited investor or institutional investor as defined in the Singapore Securities and Futures Act (Chapter 289). In using this site users represent that they are an accredited and/or Institutional investor and use this site for their own information purposes only.
The information provided on this website by Covenant Capital Pte Ltd (CCPL) is intended solely for informational purposes and should not be construed as investment advice. It does not constitute legal, tax, or other professional advice. CCPL strongly recommends consulting qualified professionals for personalized guidance. The website does not offer or solicit securities transactions, and users are expected to comply with local laws. Accredited and institutional investors in Singapore may access the information solely for informational purposes.
What types of Personal Data do Covenant Capital collect?
Personal data is any information that relates to an identifiable individual, and we may collect this information when you interact with our staffs:
1. Personal Particulars (e.g. name, address, date of birth)
2. Tax, Insurance and employment details
3. Banking information and financial details
4. Details of interactions with us (eg. Images, voice recordings, personal opinions)
5. Information obtained from mobile devices with your consent
How do we collect your Personal Data?
Below are the ways that we collect your data:
1. Investment Management Agreement forms, Risk Profile forms, Subscription forms;
2. Via emails, SMSes, Whatsapps, phone calls or any other digital means to the office or its’ staffs;
3. Photos and videos of you from our events; and
4. Information about your use of our services and website, including cookies and IP address
How do we use your Personal Data?
1. For General Support
Verify your identity before providing our services, or responding to any of your queries, feed-back and complaints.
2. For our Internal Operations
a. Aid our analysis so that the company can improve our services and products.
b. Manage the company’s day-to-day business operations.
c. Ensure that the information that the company have on you is current and up to date.
d. Conducting Due Diligence checks to reduce Money Laundering and Terrorist
3. Financing Schemes
e. Comply with all laws and obligations from any legal authorities.
f. Seek professional advice, including legal.
g. Provide updates to you.
4. Posting on LinkedIn and Website
We may post personal data, including pictures and videos, on our LinkedIn page and website for purposes such as:
Who do we share your Personal Data with?
1. Any officer or employee of the company and its related companies;
2. Third parties (and their sub-contractors if applicable) that works with us, such as Custodian Bank of choice, Fund Administrators for the Funds that we manage, any third party Fund’s Administrators, IT support who back up our database and other service providers;
3. Relevant authorities such as government or regulatory authorities, statutory bodies, law enforcement agencies.
4. Relevant authorities such as government or regulatory authorities, statutory bodies, law enforcement agencies.
5. We require all personnel of the company and third party to ensure that any of your data disclosed to them is kept confidential and secure
6. We do not sell your Personal Data to any third party, and we shall comply fully with any duty and obligation of confidentiality that governs our relationship with you
When the company discloses your personal data to third-parties, the company will, to the best of its abilities, exercise reasonable due diligence that they are contractually bound to protect your personal data in accordance with applicable laws and regulations, save in cases where by your personal data is publicly available.
Accessing and Correction Request and Withdrawal of Consent
Please contact your advisor/banker or alternatively you can contact ccops@covenant-capital.com should you have the following queries.
1. Regarding the company’s data protection policies and processes
2. Request access to and/or make corrections to your personal data in the company’s possession; or
3. Wish to withdraw your consent to our collection, use or disclosure of your personal data.
The company endeavours to respond to you within 30 days of the submission.
Should you choose to withdraw your consent to any or all use of your personal data, the company might not be able to continue to provide any further services or maintain further relationships. Such withdrawal may also result in the termination of any agreement or relationship that you have with us.
Complaints
If you wish to make a complaint with regards to the handling and treatment of your personal data, please contact the company’s Data Protection Officer, mentioned below, directly. The DPO shall contact you within 5 working days to provide you with an estimated timeframe for the investigation and resolution of your complaint.
Should the outcome of the resolution is not satisfactory, you may refer to the Personal Data Protection Commission (PDPC) for any further resolutions.
If you have any doubt, please contact Mr Tay Kian Ngiap, the PDPA Data Protection Officer for Covenant Capital Pte. Ltd. He can be reached at kntay@covenant-capital.com
By accessing this website, you hereby agree to the terms listed on the website, all applicable laws and regulations, and agree that you are responsible for compliance with any applicable local laws. Any claim relating to Covenant Capital’s website shall be governed by the laws of the Republic of Singapore without regard to its conflict of law provisions.
1. License to Use
Permission is granted to download information and materials on Covenant Capital’s website for personal, non-commercial viewing only. This is the grant of a license, not a transfer of title, and under this license you may not:
i) modify or copy the information and materials;
ii) use the information and materials for any commercial purpose, or for any public display (commercial or non- commercial);
iii) attempt to decompile or reverse engineer any software contained on Covenant Capital’s web site;
iv) remove any copyright or other proprietary notations from the materials; or
v) transfer the materials to another person or “mirror” the materials on any other server.
All content, including but not limited to logo, tagline, graphics, images, text contents, buttons, icons, design and structure are property of Covenant Capital. All content on this website is protected by copyright, patent and trademark laws.
The Covenant Capital logo should not be used for any purpose whatsoever beyond what is available on the website, unless you have obtained written approval from us.
2. Disclaimer
The materials on Covenant Capital’s website are provided “as is”. Covenant Capital makes no warranties, expressed or implied, and hereby disclaims and negates all other warranties, including without limitation, implied warranties or conditions of merchantability, fitness for a particular purpose, or non-infringement of intellectual property or other violation of rights. Further, Covenant Capital does not warrant or make any representations concerning the accuracy, likely results, or reliability of the use of the materials on its Internet web site or otherwise relating to such materials or on any sites linked to this site.
It is your responsibility to evaluate the accuracy, completeness, or usefulness of any information, advice and other content available through this website.
You should not solely rely on the information, advice and other contents available on our website for decisions on investment(s) or decision with respect to our company’s products and services. You are advised to seek additional information required for you to make sound, well-informed and reasonable decision.
3. Limitations
In no event shall Covenant Capital or its suppliers be liable for any damages (including, without limitation, damages for loss of data or profit, or due to business interruption,) arising out of the use, inability to use or user’s reliance on the materials obtained through Covenant Capital’s web site, even if Covenant Capital or a Covenant Capital authorized representative has been notified orally or in writing of the possibility of such damage.
4. No Offer
Nothing in this website constitutes a solicitation, an offer, or a recommendation to buy or sell any investment instruments, to effect any transactions, or to conclude any legal act of any kind whatsoever. The information on this web site is subject to change (including, without limitation, modification, deletion or replacement thereof) without prior notice. When making decision on investments, you are advised to seek additional information required for you to make sound, well-informed and reasonable decision.
5. Revisions and Errata
The materials appearing on Covenant Capital’s website may include technical, typographical, or photographic errors. Covenant Capital does not warrant that any of the materials on its website are accurate, complete, or current. Covenant Capital may make changes to the materials contained on its website at any time without notice. Covenant Capital does not, however, make any commitment to update the materials.
6. Site Terms of Use Modifications
Covenant Capital may revise these terms of use for its web site at any time without notice. By using this website you are agreeing to be bound by the then current version of these Terms and Conditions of Use. If any of the term or change is deemed not acceptable to you, you should not continue to browse this site.
Your privacy is very important to us and we respect your online privacy. This Policy has been developed in order for you to understand how we collect, use, communicate and disclose and make use of personal information. We are committed to conducting our business in accordance with these principles in order to ensure that the confidentiality of personal information is protected and maintained.
1. Collection and Use of Information
We may collect personal identifiable information, such as names, postal addresses, email addresses, etc., when voluntarily submitted by visitors to our website. This information is only used to fulfill your specific request, unless further permission is provided to us to use it in any other manner or for any other purpose.
2. Web Cookies / Tracking Technology
A cookie is a small file which seeks permission to be placed on your computer’s hard drive. Once you are agreeable to the use of cookies, the file is added and the cookie helps analyse web traffic and tracks visits to a particular website. Cookies allow web applications to respond to you as an individual. The web application can tailor its operations to your needs, likes and dislikes by gathering and remembering information about your preferences.
We use traffic log cookies to identify which pages are being used. This helps us analyse data about website traffic and improve our website in order to tailor it to customer needs. We only use this information for statistical analysis purposes and then the data is removed from the system.
Overall, cookies help us provide you with a better website by enabling us to monitor which pages you find useful and which you do not. A cookie in no way gives us access to your computer or any information about you, other than the data you choose to share with us.
You can choose to accept or decline cookies. Most web browsers automatically accept cookies, but you can usually modify your browser setting to decline cookies if you prefer. This may prevent you from taking full advantage of the website.
3. Links to other websites
Our website may contain links to other websites of interest. However, once you have used these links to leave our site, you should note that we do not have any control over that other website. Therefore, we cannot be responsible for the protection and privacy of any information that you provide whilst visiting such sites, and this privacy statement does not govern such sites. You should exercise caution and review the privacy statement applicable to that particular website.
4. Distribution of Information
We will not sell, distribute or lease your personal information to third parties unless we have your permission or are required by law to do so. We may use your personal information to send you promotional information about third parties’ products or services, which we think you may find interesting if you tell us that you wish this to happen.
If you believe that any information we are holding on you is incorrect or incomplete, please write to or email us as soon as possible at the above address. We will promptly correct any information found to be incorrect.
When required by law, we may share information with governmental agencies or other companies assisting in the investigations. The information is not provided to these companies for marketing purposes.
5. Commitment to Data Security
To make sure your personal information is secured, we communicate our privacy and security guidelines to all Covenant Capital’s employees and strictly enforce privacy safeguards within the company.
Your personal identifiable information is kept secure. Only authorised employees, agents and contractors who have a direct need to access the information will be able to view this information.
We reserve the right to make changes to this policy. Any changes to this policy will be posted.
